Two Major Federal Student Loan Updates Could Offer Borrowers Some Relief. Here’s What to Know

Student loans have a way of sticking around long after graduation. For some borrowers, it’s the interest that makes paying down their balance feel like an uphill battle. For others, missed payments have turned into a much bigger financial headache. But two recent federal changes could offer some breathing room, whether you’re keeping up with your bills or struggling to get back on track. And one of those opportunities comes with a deadline borrowers won’t want to miss.
The Pressure On Borrowers Has Been Building
More than 42 million Americans hold federal student debt totaling over $1.7 trillion. The average balance has climbed to $40,768, according to Education Department data. Meanwhile, repayment rules have changed repeatedly, making it difficult for some borrowers to plan ahead. The latest announcements won’t erase those challenges, but they introduce two practical opportunities worth understanding.
The First Change Gives Borrowers More Time
The Education Department has extended the deadline to enroll in automatic payments and qualify for an enhanced interest-rate discount. Originally scheduled to expire September 30, the enrollment window now runs through December 31, 2026. That gives eligible borrowers another three months to sign up. The potential savings are especially relevant for people carrying larger balances.
The Discount Is Bigger Than Before
Federal borrowers using autopay traditionally received a 0.25-percentage-point interest-rate reduction. Under the temporary incentive, eligible borrowers receive a full 1-percentage-point reduction instead. Someone with a 6% rate, for example, could see it fall to 5%. That’s not a 1% reduction in the loan balance, but it can reduce interest charges over time.
The Savings Could Add Up
Consider a borrower with a $40,000 balance. A one-percentage-point rate reduction would mean roughly $400 less in annual interest at that balance, before accounting for payments and a declining principal. Actual savings depend on the loan’s balance, repayment schedule and how long the discount applies. The benefit is temporary, running through June 30, 2028, rather than permanently changing the loan’s interest rate.
Not Every Federal Loan Qualifies
The enhanced discount applies to eligible Direct Loans issued on or after July 1, 2012. These include Direct Subsidized, Direct Unsubsidized, Direct PLUS and Direct Consolidation Loans. Some Parent PLUS borrowers can qualify, too. Loans must be in good standing, so borrowers already in default generally need to resolve that status before receiving the benefit. That distinction leads directly to the second federal update.
Enrolling In Autopay Is Straightforward
Eligible borrowers can sign into their student loan servicer’s account, select automatic payments and provide checking or savings account information. Monthly payments are then withdrawn automatically. Borrowers already enrolled in autopay received the enhanced discount automatically, according to the Education Department. Nearly 2 million borrowers have enrolled since the larger incentive was announced, suggesting considerable interest in reducing borrowing costs.
The Second Change Targets Borrowers In Default
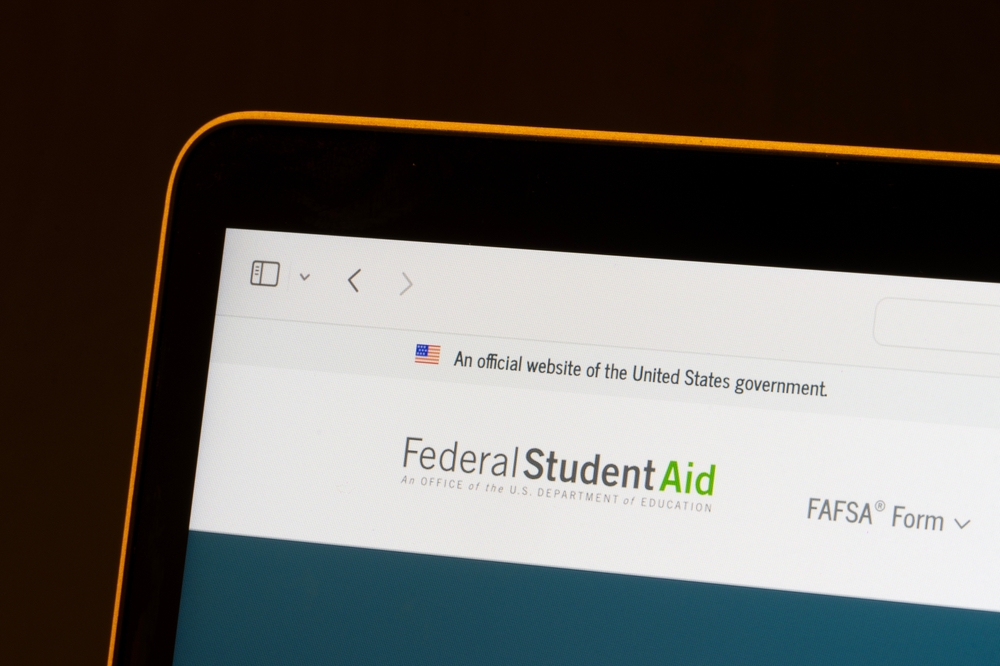
For people who have fallen seriously behind, a lower interest rate may not be their most immediate concern. The Education and Treasury departments have launched a Defaulted Loans Support Center through StudentAid.gov. The online service is designed to help borrowers understand their options and take steps toward returning their federal loans to good standing.
Getting Out Of Default Could Become Simpler
Previously, resolving a default could involve paperwork submitted through the mail or even by fax. The new portal brings several tasks online, including reviewing repayment options, making payments and applying for loan rehabilitation or consolidation. Borrowers can also explore potential discharge options. The goal is to make the process easier to navigate, although eligibility requirements and repayment obligations still apply.
What Borrowers Should Watch Next
The two updates offer different kinds of relief, but neither automatically eliminates student debt. Borrowers in good standing have until December 31 to secure the temporary interest discount, while those in default can explore the new online support center now. With roughly 9.3 million federal borrowers in default as of June 30, the bigger test will be whether these changes help people make lasting progress toward manageable repayment.