Turning 73 Could Trigger a Tax Surprise on Your Social Security
Retirement birthdays usually mean celebrations, family gatherings, and another year of freedom from work. But turning 73 can also introduce an unwelcome financial surprise. Some retirees discover that money they carefully saved for decades must suddenly come out of their retirement accounts. Those withdrawals can increase their taxable income and potentially make more of their Social Security benefits subject to federal taxes. The surprising part is that nothing about their monthly Social Security benefit necessarily changes. Instead, a separate retirement rule can quietly change how much they keep.
This article was created with the assistance of AI and reviewed by our editorial team for accuracy and clarity.
The IRS Has a Rule for Retirement Savings
Traditional IRAs and most workplace retirement plans offer a valuable advantage: money generally grows without being taxed until withdrawal. However, the government doesn’t allow those tax-deferred savings to remain untouched indefinitely. Eventually, account owners must begin taking required minimum distributions, commonly called RMDs. These mandatory withdrawals ensure that some retirement savings become taxable income during the owner’s lifetime. For retirees already withdrawing enough to cover expenses, the requirement may change very little. But people who prefer leaving their savings invested could face an entirely different situation.
Age 73 Is Important, but Not for Everyone
Under current rules, people born between 1951 and 1959 generally begin RMDs for the year they turn 73. Those born in 1960 or later generally start at 75. The distinction matters because retirement planning advice sometimes treats age 73 as universal. It isn’t. The required withdrawal amount depends largely on the previous December’s account balance and an IRS life expectancy factor. Someone with substantial traditional retirement savings could therefore face a meaningful annual withdrawal. And that required payment can create consequences beyond the ordinary tax owed on retirement income.
Here’s How Retirement Withdrawals Affect Social Security

The potential surprise comes from how federal taxes on Social Security are calculated. Traditional IRA and 401(k) withdrawals generally increase adjusted gross income. That higher income can also increase what’s called provisional income, a figure used to determine whether Social Security benefits are taxable. Provisional income generally combines adjusted gross income, tax-exempt interest, and half of annual Social Security benefits. If mandatory retirement withdrawals push that total beyond certain thresholds, part of the benefits becomes taxable. It’s an indirect connection, but one that can substantially change a retiree’s tax return.
The Income Thresholds Are Surprisingly Low
For single filers, Social Security benefits may become taxable when provisional income exceeds $25,000. For married couples filing jointly, the threshold is $32,000. At higher income levels, above $34,000 for singles or $44,000 for joint filers, up to 85% of benefits can become taxable. That doesn’t mean the government takes 85% of someone’s Social Security check. It means up to 85% of the benefits may be included in taxable income. Understanding that difference helps explain the real financial risk without making it sound worse than it is.
A Simple Example Shows How the Surprise Happens

Consider a single retiree receiving $24,000 annually from Social Security and $12,000 from other taxable income. Before any required withdrawal, provisional income would be approximately $24,000, below the initial taxation threshold. Now suppose an RMD adds $15,000 in taxable retirement income. Provisional income rises to approximately $39,000, potentially making up to 85% of Social Security benefits taxable under federal rules. The exact tax depends on deductions and other circumstances. Still, the example illustrates how a withdrawal from one account can affect income from another.
The First Withdrawal Deadline Can Make Things Worse
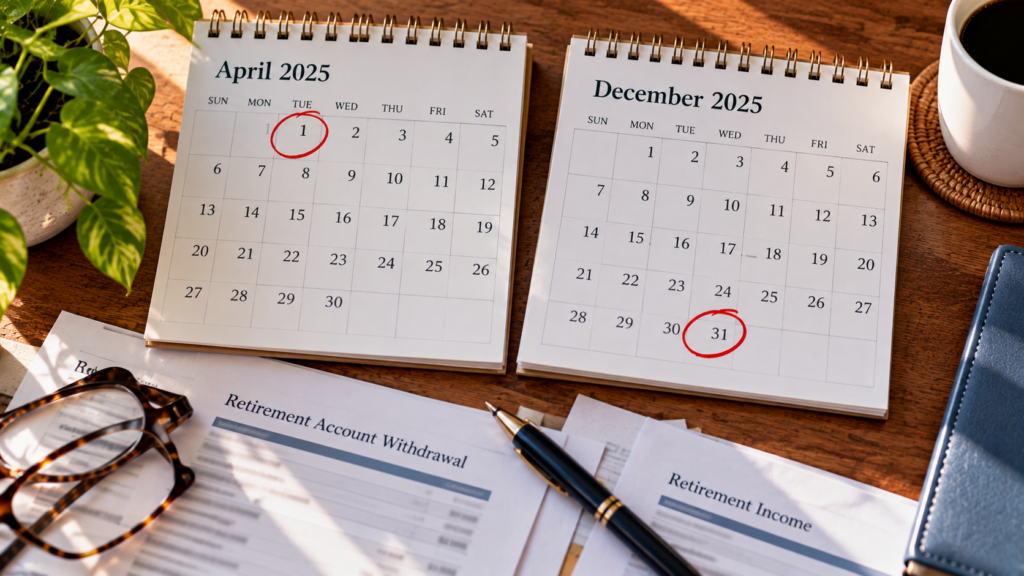
Most RMDs must be completed by December 31, but the first required withdrawal has a special deadline. Eligible retirees can postpone it until April 1 of the following year. That flexibility sounds attractive, particularly when someone isn’t ready to withdraw money. However, delaying the first RMD means taking two required distributions during the same calendar year. The combined amount could increase taxable income and affect Social Security taxation more sharply. Missing an RMD entirely can also trigger an IRS penalty, generally 25% of the shortfall, potentially reduced to 10% through timely correction.
Roth Accounts Offer a Different Tax Arrangement

Roth retirement accounts work differently because contributions generally involve money that has already been taxed. Qualified withdrawals are usually tax-free and don’t increase adjusted gross income. Roth IRAs and designated Roth accounts in workplace plans also avoid lifetime RMDs for their original owners. Consequently, retirees with Roth savings may have greater flexibility when deciding how to fund expenses without increasing Social Security taxation. However, Roth accounts don’t automatically make benefits tax-free. Pensions, investment income, and other taxable sources can still push provisional income above the applicable thresholds.
Planning Ahead May Reduce the Tax Impact
Retirees approaching RMD age may consider converting some traditional retirement savings into a Roth IRA before mandatory withdrawals begin. Such conversions can reduce future traditional account balances, potentially lowering later RMDs. However, converted amounts are generally taxable in the conversion year and could themselves increase Social Security taxation. Another option for eligible retirees is a qualified charitable distribution, which sends money directly from an IRA to an eligible charity. These distributions can satisfy RMD requirements without adding the donated amount to adjusted gross income. Both strategies require careful consideration of individual circumstances.
The Best Time to Prepare Is Before 73
For retirees approaching their first mandatory withdrawal, the next step is reviewing account balances, income sources, and expected tax obligations before the deadline arrives. A financial or tax professional can help estimate RMD amounts and determine whether withholding additional taxes makes sense. Some people may also qualify for the temporary additional senior deduction available from 2025 through 2028, although income limits apply. The important development isn’t simply reaching another birthday. It’s entering a stage when retirement withdrawals become less optional, making advance tax planning increasingly valuable for protecting future income.