Florida Homeowners Have a Bigger Problem Than Property Taxes, and It’s Hitting Their Wallets Hard

Florida homeowners are facing a costly problem that may be more pressing than property taxes: the price of insuring their homes. A September 2026 survey of 1,511 Florida homeowners found that 63% were more concerned about property insurance costs than property taxes, despite the political attention surrounding proposed tax relief. Insurance premiums, coverage cancellations and uncertainty about future costs are putting pressure on household budgets across the state, leaving many homeowners questioning whether recent reforms will deliver meaningful relief.
Insurance Costs Are Outpacing Property Tax Concerns
The survey conducted by the University of North Florida’s Public Opinion Research Lab in partnership with the Orlando Sentinel and South Florida Sun Sentinel found that 63% of respondents were more worried about insurance than property taxes, while 36% said taxes were their bigger concern. Insurance ranked as the greater worry among a majority of homeowners across political affiliations and regions of Florida. The findings highlight a gap between the tax debate dominating headlines and the expense many residents say is hitting them hardest.
Florida Has Some of the Nation’s Highest Insurance Costs
The cost of home insurance in Florida is high by national standards, especially for properties exposed to hurricanes and wind damage. U.S. Census Bureau data for 2023 showed that the median annual property insurance cost for Florida households with a mortgage was $2,273, the highest among the states in that analysis. A 2026 Government Accountability Office report also found that insurance premiums as a share of median household income were highest in Florida, Louisiana and Oklahoma, underscoring how much the expense can weigh on household finances.
Many Homeowners Have Already Switched Insurers
The survey found that 54% of respondents had switched their primary home insurer at least once over the previous five years, and 33% had changed companies twice or more. Among homeowners who switched, 47% said they had been dropped by an insurer, including some whose companies stopped operating in Florida. Across the full survey, one in four homeowners said they had lost coverage at least once during that period, illustrating how insurance availability can be a problem alongside rising prices.
Premiums Have Jumped Sharply for Some Families
Nearly half of the surveyed homeowners, or 47%, said their annual premiums had increased by at least 50% over five years. Another 19% said their premiums had risen by that much in just the previous year, a particularly steep increase for families already dealing with mortgage payments, utilities and maintenance. Individual costs vary according to location, building type, replacement value, storm protection and deductibles, but the survey suggests that large premium increases have become a common experience for many Florida households.
Insurance Claims Can Bring Another Financial Shock
Higher premiums do not always guarantee that a claim will be approved quickly or paid in full. Among the 261 respondents who had filed an insurance claim in the previous five years, 45% said their claim was initially denied. A denial does not necessarily mean the insurer acted improperly, since claims can be rejected for different reasons, but homeowners may face additional costs and disputes when they believe storm or property damage should be covered.
Hurricanes and Wind Risk Help Drive the Problem
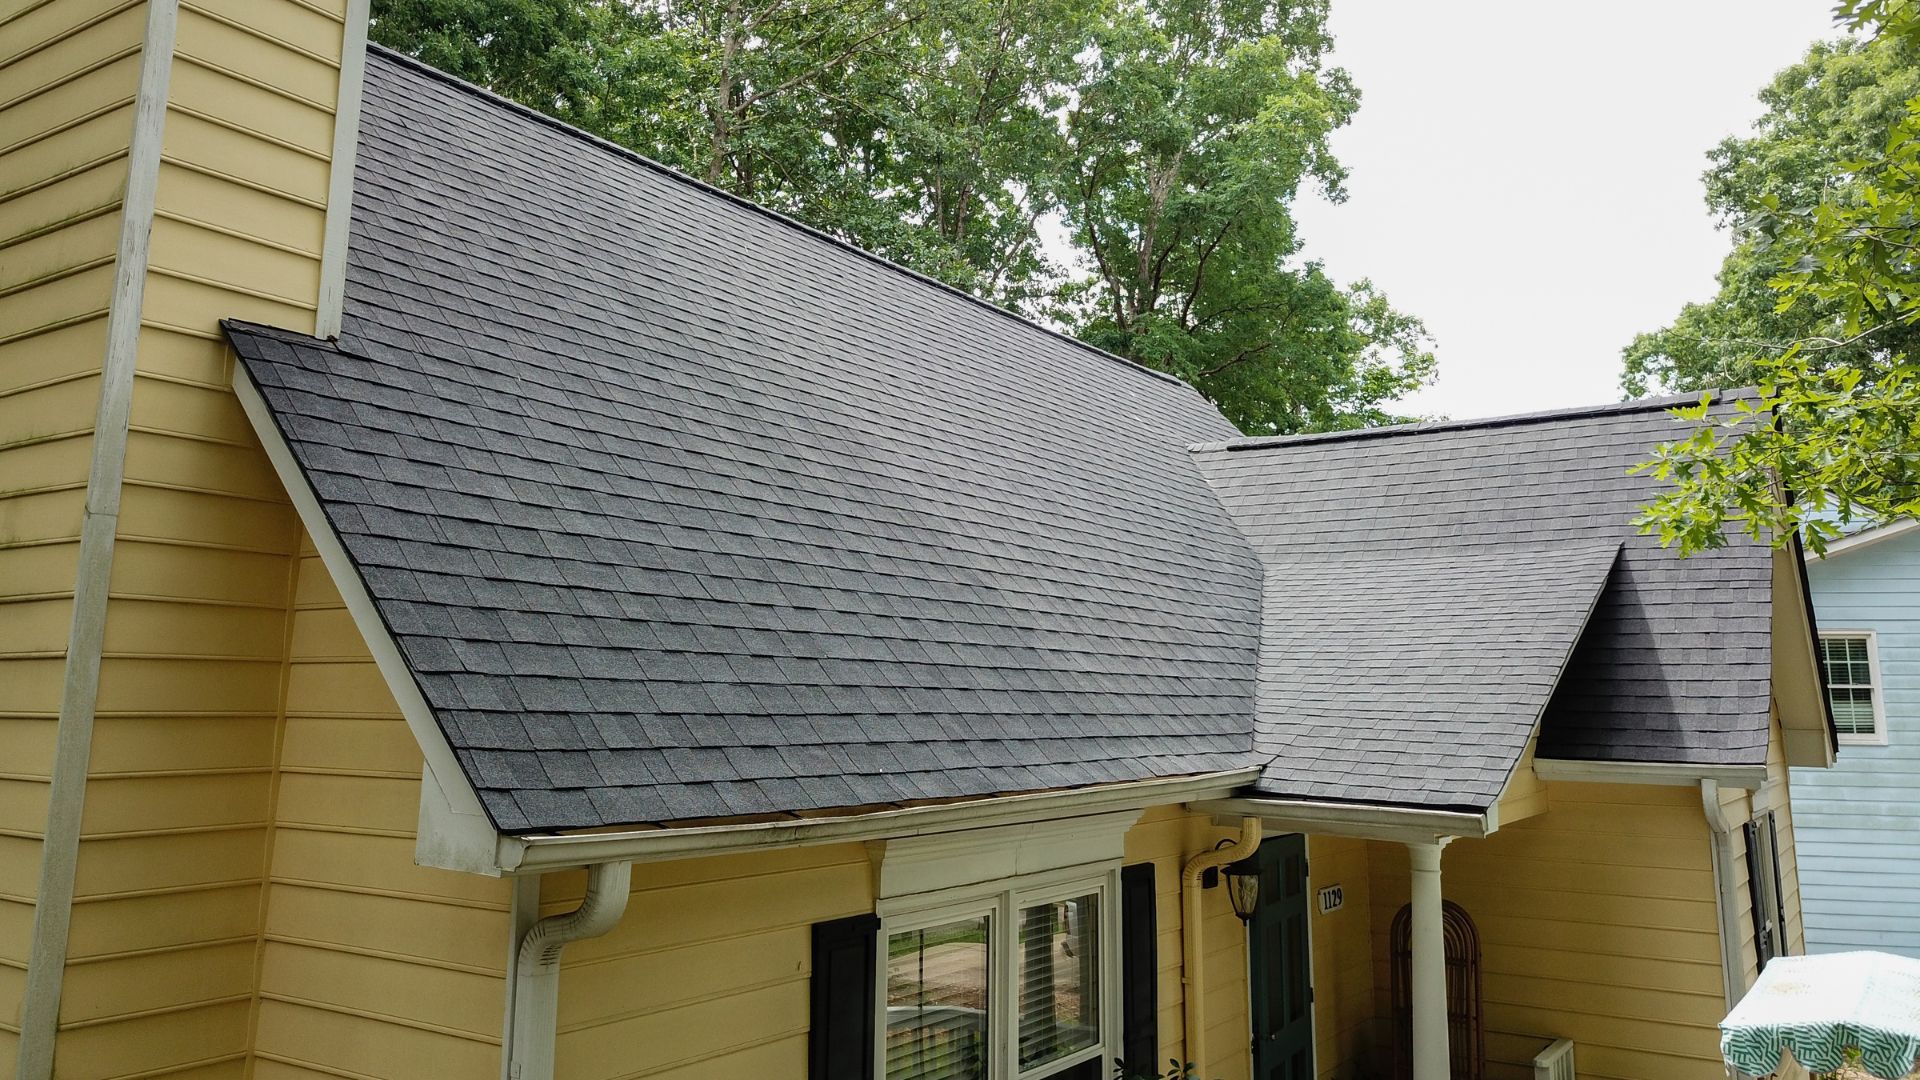
Florida’s exposure to hurricanes, severe storms and wind damage is a major factor affecting insurers’ costs and willingness to offer coverage. The Government Accountability Office reported in 2026 that homes in areas with high wind-damage risk had insurance premiums about 58% higher than comparable homes in areas with medium wind risk. Insurers must account for potential catastrophic losses as well as reinsurance and rebuilding expenses, and the higher risk can also make some companies less willing to insure properties in vulnerable areas.
Many Residents Are Skeptical of Insurance Reforms
Florida lawmakers have introduced reforms intended to stabilize the insurance market, but many homeowners remain unconvinced that the changes are helping them. In the 2026 survey, 55% said they saw no signs the market was improving, while 26% believed it was getting worse and 18% thought conditions were improving and rates might fall. When asked who had benefited most from the reforms, 69% pointed to the insurance industry, compared with 16% who said consumers had benefited.
Property Tax Relief May Not Solve the Bigger Problem
Proposals to reduce property taxes could still help eligible homeowners, but lower taxes would not automatically make insurance more affordable or guarantee that coverage remains available. Florida’s insurance costs can vary widely by county, construction type, home value and protective features, so homeowners need to compare actual policy quotes rather than rely on statewide averages. The state’s Office of Insurance Regulation provides a homeowners rate comparison tool that residents can use to review sample rates from participating insurers, although individual quotes will differ.
Homeowners Are Looking for Relief They Can Actually Feel
Florida’s insurance problem has become a central household budget concern at a time when residents are also watching property taxes, utility bills and other living expenses. The latest survey suggests that homeowners want more than promises of reform: they want stable coverage, understandable policy terms and premiums they can afford to pay year after year. Until insurance costs and availability improve in a sustained way, many Florida homeowners may continue to see protecting their homes as a more urgent financial challenge than reducing their property tax bills.