Wall Street Says Trump’s Plan to Fix the Housing Crisis Won’t Work Because the Model It’s Based On Already Failed

The United States is short somewhere between 7 and 10 million homes, mortgage rates remain well above the historic lows millions of Americans locked in during the pandemic, and the market has now been effectively frozen for close to three years. Against that backdrop, the Trump administration released its most detailed housing plan to date, and within days, analysts at UBS published a research note with a pointed conclusion: well-intentioned, directionally right in places, but not the fix the market needs.
The White House strategy rests on a straightforward argument: excessive government regulation has made housing unaffordable. The administration calls this burden a “bureaucrat tax” and estimates it adds more than $100,000 to the cost of a single-family home. The administration estimates that a one-standard-deviation decline in the Wharton Residential Land Use Regulatory Index could increase the U.S. housing stock by 13.2 million units. To illustrate the concept, the White House pointed to Texas in the early 2000s, when looser land-use rules enabled rapid suburban expansion and kept home prices stable even as the state’s population surged.
The problem with that example is what happened next. Austin had become overvalued by 41% and Dallas by 33% by 2022. The correction that followed has been steep and prolonged. Austin now ranks 51st out of 52 large U.S. cities in housing market health, with a composite score of 17.2, making it the second-weakest large-city market in the country. The same model Washington is now citing as a blueprint has, in real time, produced one of the most significant housing corrections of any major American metro in recent history.
Why Deregulation Alone Has Structural Limits That Washington Cannot Override
The central tension in the administration’s housing strategy is jurisdictional. Housing regulation in the United States is overwhelmingly controlled by local governments, not the federal government. That means the guidelines coming out of Washington are, in practice, voluntary recommendations. States with the heaviest regulatory burdens, including California and those in New England, are under no legal obligation to adopt the White House’s approach, and according to UBS analysts, may prove unwilling to do so.
This is not a new concern. In a research note released in January, Morgan Stanley strategists James Egan and Jay Bacow characterized President Trump’s housing directives as only “modestly helpful for homeowner affordability,” warning that they amount to a marginal adjustment rather than a market cure. The administration had directed Fannie Mae and Freddie Mac to purchase $200 billion in mortgage-backed securities, a move that briefly pushed the 30-year mortgage rate below 6% for the first time since 2022. The effect was real but short-lived, and Morgan Stanley’s revised year-end mortgage rate forecast moved only from 5.75% to 5.6%.
The deeper structural obstacle is what analysts call the “lock-in” effect. Roughly two-thirds of all outstanding mortgages still carry interest rates below 5%, meaning homeowners have little financial incentive to sell no matter how much deregulation Washington pushes through. Apollo Global Management’s Torsten Slok noted that 40% of U.S. homes carry no mortgage at all, making the lock-in effect even deeper than mortgage data alone suggests. The result is a market with very few sellers, regardless of what happens on the supply side.
The Texas Cautionary Tale That the White House Did Not Mention
Supply elasticity, the ability of builders to quickly add homes when demand rises, is the feature that made Texas a plausible model for deregulation advocates. When land is available and zoning is flexible, construction can scale up relatively fast. But according to Lance Lambert, editor-in-chief of ResiClub, that same elasticity runs in both directions. When demand cools, the additional supply coming online amplifies downward pressure on prices and rents, producing the boom-bust cycle Texas cities are currently navigating.
Austin’s housing market has recorded four consecutive years of price declines from a median peak of $550,000. The correction is ongoing and well-documented. Markets in the Northeast and coastal California, by contrast, tend to see less dramatic swings precisely because limited buildable land constrains supply responses in both directions. The administration’s model is not wrong in its mechanics, it is simply incomplete. Deregulation without coordinated demand management has historically produced volatility as often as stability, a dynamic the Texas data now illustrates clearly.
None of this means supply-side reform is the wrong long-term direction. Lambert told Fortune directly that making it easier to build in more markets over time would allow supply to respond more effectively to cyclical spikes in housing demand, pointing to the 2020 to 2022 period as an example of the kind of surge a more elastic national market could better absorb. The issue is timing. What the administration is proposing is a decade-long structural intervention. The question Wall Street is asking is what happens to American homebuyers and renters in the years before that structure takes hold.
There Is One Part of the Plan That Analysts Actually Support, and It Is Not Quick Either
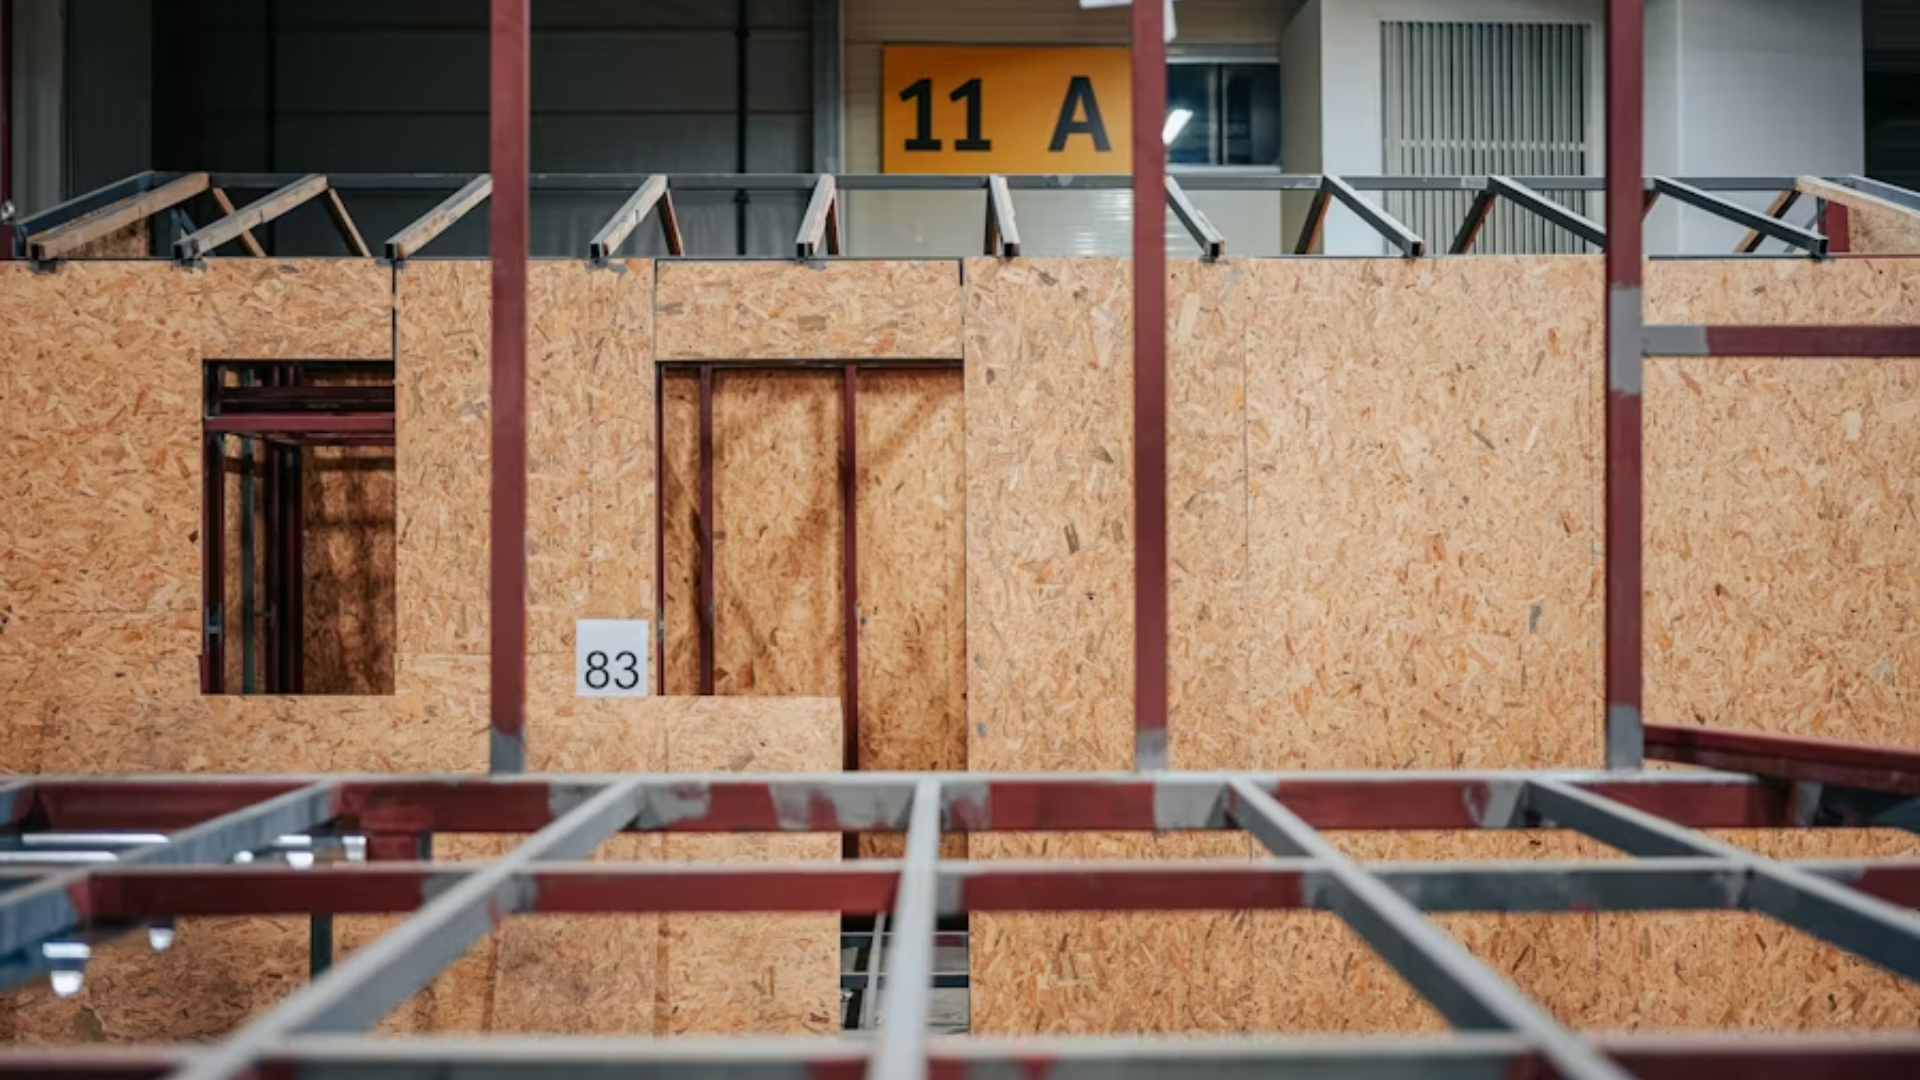
UBS expressed genuine enthusiasm for one specific element of the administration’s housing strategy: off-site and modular construction. The data behind that enthusiasm is concrete. Construction labor productivity declined roughly 30% between 1970 and 2020, a drag the administration estimates has cost the U.S. economy about 20 basis points of GDP growth per year, while overall U.S. productivity rose by 100% over the same period. That gap is significant, and factory-built construction offers a credible path toward closing it.
UBS estimates wall panelization alone could generate $6,200 in per-home cost savings at scale, 30% fewer framing days, and 20% less waste. The administration’s report recommended aligning building codes for modular and prefabricated housing with national standards, which UBS identified as a potential catalyst for efficiency gains across the entire housing value chain. For a sector where costs have climbed steadily and labor has become harder to source, those numbers represent a meaningful opportunity if the policy framework to support them follows through.
The gap between where the housing market is now and where any of these interventions could take it remains wide. UBS identified expanding Fannie Mae and Freddie Mac mortgage-backed securities purchases, or cutting the guarantee fees those entities charge lenders, as the fastest lever available to the administration if it wants to move the needle before the midterms. Modular construction, zoning reform, and deregulation are the right long-term tools, but they are measured in years. For the millions of Americans currently priced out of homeownership or locked into homes they cannot afford to leave, the timeline of the solution is itself part of the problem.